
Allowances at a glance
| Item | Allowance | Conditions |
|---|---|---|
| New goods, gifts and food (GST import relief) | Up to S$500 | Away 48 hours or more; for personal use |
| New goods, gifts and food after a short trip | Up to S$100 | Away less than 48 hours |
| Liquor | One of 5 combinations, up to 2 litres | Age 18 or above; at least 48 hours abroad; not arriving from Malaysia; for personal consumption |
| Cigarettes and tobacco | No duty-free concession | Duty and GST on every pack, including SDPC-marked packs bought in Singapore |
| Liquor over 10 litres or tobacco over 0.4 kg | Customs permit required | TradeNet permit through a freight forwarder or declaring agent |
| Cash and bearer negotiable instruments | Report amounts over S$20,000 | Form NP 727 online within 72 hours before arrival |

Duty-free liquor combinations
| Option | Spirits | Wine | Beer |
|---|---|---|---|
| A | 1 litre | 1 litre | – |
| B | 1 litre | – | 1 litre |
| C | – | 1 litre | 1 litre |
| D | – | 2 litres | – |
| E | – | – | 2 litres |
Japanese drinks and the liquor concession
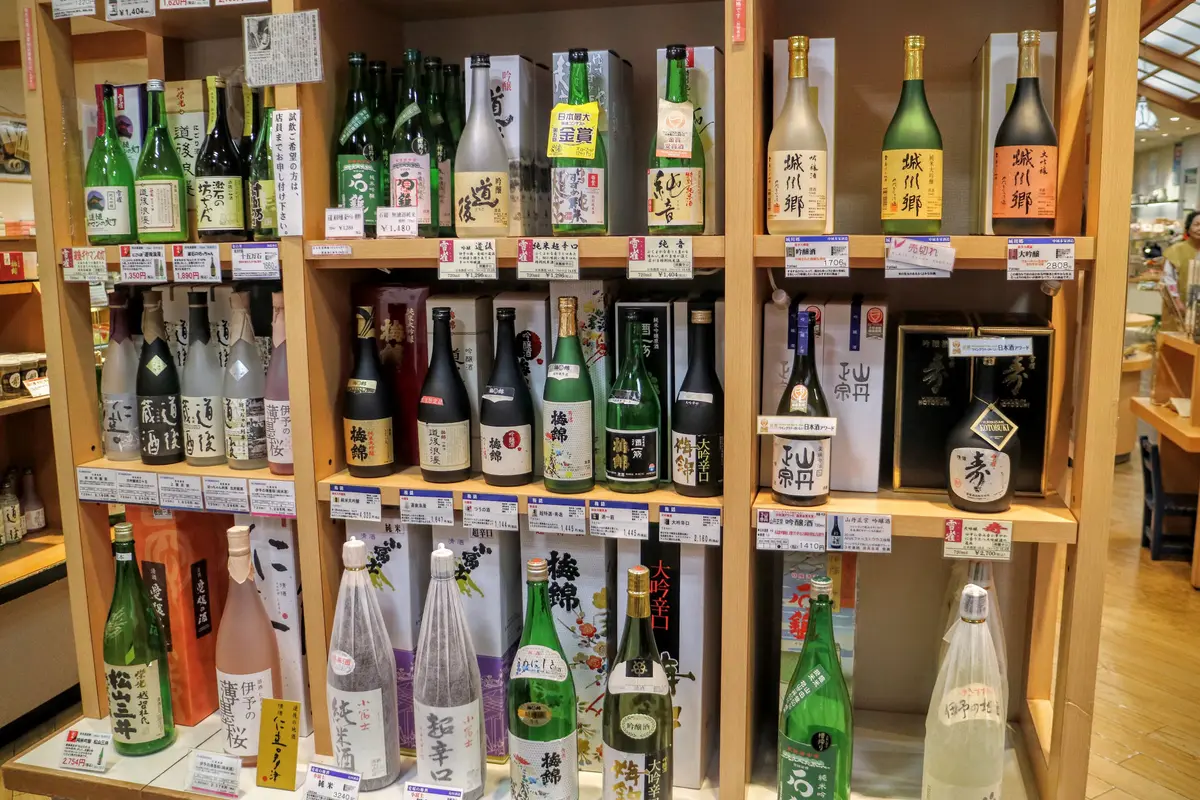
Singapore Customs counts sake as wine and umeshu and soju as spirits. Cooking wine, rice wine and drinks taken for health reasons, such as Yomeishu, are also covered by the concession.
The concession applies to liquor bought overseas or at duty-free shops in Singapore, for your own consumption only. Duty and GST are payable on liquor beyond your chosen option and on any liquor carried for someone else.
How GST import relief is calculated
GST import relief covers new articles, souvenirs, gifts and food preparations bought overseas for personal use. GST is charged at the prevailing rate on the value above your relief, and IRAS gives the current rate as 9%. It is payable whether or not foreign sales tax was paid or refunded. Japan’s tax-free shopping removes Japanese consumption tax only and does not reduce GST in Singapore.
Singapore Customs gives this example: for a S$2,000 bag bought overseas after 48 hours or more away, GST is charged on S$2,000 minus S$500, which at 9% comes to S$135. A new item remains new even if you use it during the trip; only items you owned before leaving Singapore count as used articles.
Liquor, tobacco and goods for commercial purposes are excluded from GST import relief. Holders of a work permit, employment pass, student pass, dependant pass or long-term pass, and crew members, are not eligible. Keep your receipts: without one, the value is assessed from identical or similar goods.
Food limits set by SFA
| Food | Source | Limit per traveller |
|---|---|---|
| Beef, pork and poultry, including any food containing meat | Japan is an approved source | 5 kg of meat in total |
| Mutton | Japan is not an approved source | Not allowed from Japan |
| Fish products such as dried fish and canned tuna | All countries and regions | 5 kg in total, of which up to 2 kg frozen cooked crab or prawn meat |
| Fruits and vegetables | All countries and regions | A small, hand-carry quantity |
| Chicken shell eggs | Japan is an approved source | 30 eggs |
| Other processed food such as biscuits, jam, milk and nuts | All countries and regions | 5 kg or 5 litres in total, worth up to S$100 |
Useful before you fly
Airport transfer when you have a lot of shopping bags
Luggage storage in Tokyo for the hours before an evening flight
Items not allowed or restricted
- Chewing gum, except HSA-approved oral dental and medicinal gum
- E-cigarettes, vaporisers and their parts, shisha, chewing tobacco and snuff
- Cigarettes and tobacco without Singapore’s Standardised Packaging; they are disposed of at the checkpoint even if duty and GST were paid
- Nicotine products obtained outside Singapore, including nicotine gum, lozenges and patches
- Chilled shucked raw oysters, chilled crabmeat and food containing hemp seeds
- Medicines above a 3-month supply, or containing controlled substances without prior HSA approval
- Food brought in for sale, including sale to friends or online
Arrival in Singapore
Add up your purchases
Total the value of new goods, gifts and food bought abroad, check your liquor against one option, and list any tobacco.
Declare and pay online
The Customs@SG web application accepts declarations and payment up to 3 days before arrival, by card, PayNow, Apple Pay or Google Pay. After paying, exit through the Green Channel and show the e-receipt if stopped. The e-receipt is valid only for the arrival date shown.
Or use the Red Channel
If you have not paid in advance, declare at the Red Channel or pay at a Customs Declaration Kiosk at the checkpoint. Controlled goods cannot be declared online and must be presented with their permit at the Red Channel.
Report cash
If you carry more than S$20,000 in cash or bearer negotiable instruments, submit Form NP 727 within 72 hours before arrival on the ICA website or the MyICA app.
Penalties for not declaring
Failing to declare or under-declaring is an offence. Composition amounts for a first offence are S$200 per packet of cigarettes, 10 times the duty for other dutiable goods and up to 20 times the GST for non-dutiable goods, with a minimum of S$50. Where the penalty exceeds S$5,000, offenders may be prosecuted without an offer of composition.